Just had a car accident? Use this checklist to work through what to do at the scene, what to do about towing, and what to do in the days afterwards. Pick your state to see when you are legally required to report the crash, the minimum liability insurance you must carry, and whether your state uses no-fault insurance. Every state rule links to the official statute or agency page we checked in October 2026.
Disclaimer: TowCars.com is a nationwide towing information and referral service. We don’t tow, dispatch, or store vehicles, and we aren’t responsible for the work, prices, or conduct of any towing company. This page is information only, not legal, insurance or financial advice. See our disclosure.
After a car accident: step-by-step checklist
Tick off each step as you go. Your progress saves on this device. Pick your state to see when the law says you must report the crash, the minimum insurance you need, and whether your state uses no-fault insurance, each with a link to the official source.
Your checklist
Your state’s rules
Choose a state to see its crash-reporting rule, minimum car insurance and insurance system.
Need a tow from the scene?
If your car can’t be driven, you can usually choose your own tow company when police don’t need the road cleared right away. Tell the dispatcher where you want the car taken.
Request a tow quote Car already towed? Find the lotTowCars.com is a referral service. We don’t tow vehicles and aren’t responsible for any tow company’s work or prices.
What to do right after a car accident
The first few minutes matter most. Check for injuries and call 911 if anyone is hurt. Make the scene safe with hazard lights and, if the cars can be driven and no one is injured, move them out of the traffic lanes if it is safe and your state allows it. Then exchange information with the other driver and take photos before the vehicles are moved or towed.
- Information to collect: the other driver’s name and phone number, driver’s license number, plate number, insurance company and policy number, and the vehicle’s make, model and color.
- Photos to take: every vehicle from all sides, close-ups of damage, plates, the whole scene including traffic signs and signals, road conditions, and the other driver’s insurance card.
- Notes to write down: the time and exact location, what happened in your own words, witness names and numbers, and the responding officer’s name, agency and report number.
Your own tow vs. a police rotation tow
If your car can’t be driven, it will leave the scene in one of two ways. Which one it is affects who you deal with, what you pay and where the car ends up.
Your own tow (you choose the company)
- You call a tow company yourself, or use roadside assistance through your insurer, auto club or car maker.
- You decide where the car goes: your home, a body shop you trust or your insurer’s preferred shop. Towing straight to the repair shop avoids paying for a second tow later.
- The price is whatever you agree to, so ask for the hook-up fee, the per-mile rate and any storage charge before the truck is dispatched.
Rotation tow (police call the tow company)
- If you are injured, arrested, or can’t arrange a tow, or the car has to be cleared quickly for safety, police call the next company on their rotation list or a company under contract.
- The car usually goes to that company’s storage lot, and daily storage fees typically start right away. Ask the officer for the company name and lot address.
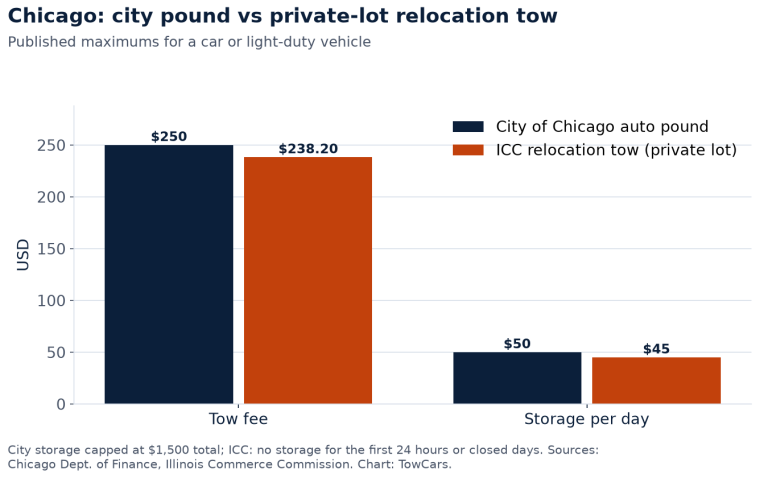
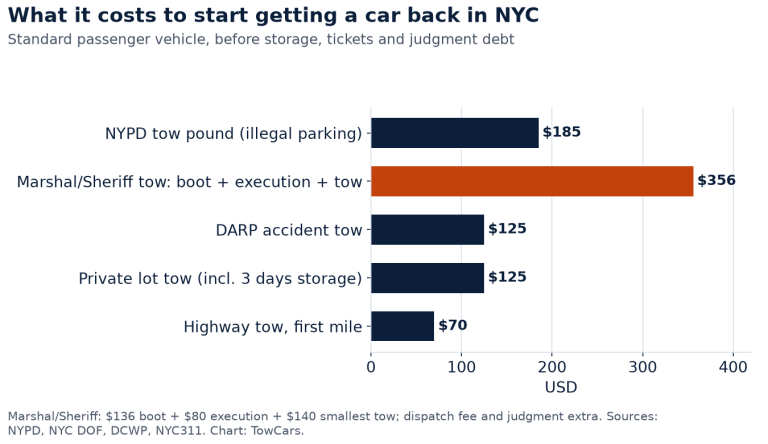
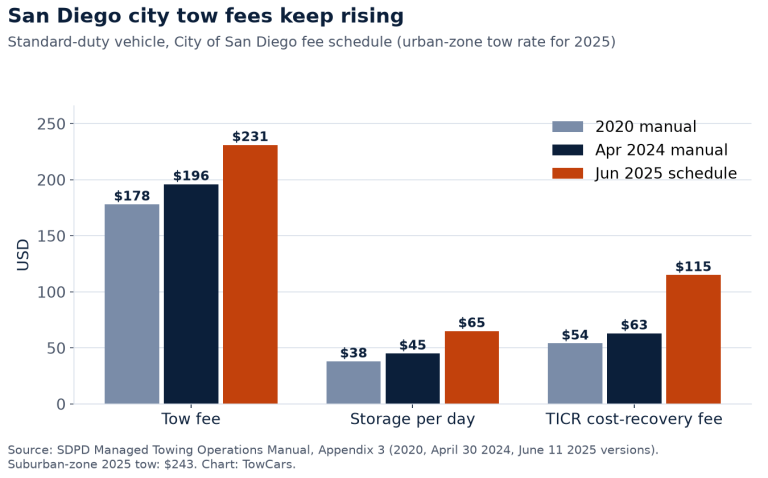
- Many cities and states set maximum rates for police-ordered tows. Compare your bill with them in our tow bill checker.
- To get the car back, you’ll usually need ID, proof of ownership and payment, and sometimes a police release. Our impound lot finder lists official lookup tools for 25 major cities.
Be careful with tow trucks nobody called. If a truck arrives that neither you nor police requested, ask who sent it before you agree to anything, and never sign a blank or unclear authorization form.
Crash reporting and insurance rules by state
The table shows each state’s minimum liability insurance and its insurance system. The last column links to the statute or agency page with that state’s crash-reporting rule. For the full rule in plain English, pick the state in the checklist above.
Frequently asked questions
Do I have to call the police after a minor car accident?
It depends on the state and on the damage. Many states require you to notify police right away when anyone is hurt or when damage passes a dollar amount, for example $500 in Florida and Georgia, $1,000 in Michigan and $3,000 in Hawaii. Some states, including Ohio and Virginia, instead require you to stop and exchange information with the other driver. Pick your state in the checklist above to see the rule and its official source.
How long do I have to report a car accident to the DMV?
Deadlines range from 72 hours to 30 days where a written report is required. Vermont and Oregon require a report within 72 hours, Washington within 4 days, California, New York and New Jersey within 10 days, Tennessee within 20 days, and Alabama and Arkansas within 30 days. Many other states only require you to notify police immediately. These deadlines apply in addition to any deadline in your insurance policy.
What is the difference between a no-fault and an at-fault state?
In a no-fault state, your own personal injury protection (PIP) coverage pays your medical bills first, whoever caused the crash, and your right to sue for pain and suffering is limited unless the injury passes a threshold. According to the Insurance Information Institute, 12 states have no-fault laws: Florida, Hawaii, Kansas, Kentucky, Massachusetts, Michigan, Minnesota, New Jersey, New York, North Dakota, Pennsylvania and Utah. Kentucky, New Jersey and Pennsylvania let drivers choose. In every other state, the driver who caused the crash is responsible through their liability insurance.
Can I choose my own tow company after an accident?
Often yes, if your car isn’t blocking traffic and police don’t need it moved right away. If you can’t arrange a tow, or the road has to be cleared, the officer usually calls a company from the agency’s rotation list or one under contract, and the car goes to that company’s lot. Either way, ask where the car is going and what it will cost.
Who pays for the tow after a car accident?
It depends on your policy and who was at fault. Towing and storage may be covered by your own collision or roadside coverage, or claimed from the at-fault driver’s liability insurer. Ask your insurer before you pay if you can, keep every receipt, and move the car out of storage quickly, because daily storage fees add up.
My car was towed from the crash and I don’t know where it is. What do I do?
Call the police department that handled the crash and ask for the tow company and lot address, or check the report. Our impound lot finder lists official lookup tools and lots for 25 major US cities.
Need a tow after an accident?
Send us the pickup location and where the car needs to go, and we’ll pass your request to independent towing providers in your area.
This checklist is general information, not legal or insurance advice. State laws change and may have exceptions not shown here. For your specific situation, read the linked official source or talk to your insurer or a lawyer.